A will only handles what happens after a parent dies. It says nothing about who pays the bills if the parent is alive but cannot. It says nothing about what medical treatment the parent does or does not want. It says nothing about who has the legal authority to talk to the bank, the doctor, or the Medicaid office. For most aging families, the gap a will leaves is years long and very expensive to fill in late.
Not legal or financial advice: General information, not legal/financial advice. Laws and benefits vary by state — consult a licensed attorney or financial advisor.
This guide walks through the five documents every aging parent actually needs — what each one does, why a will alone is not enough, and the order most families build them in. None of this is a substitute for an elder-law attorney's advice; it is the framework to bring to one.
Document one: financial power of attorney
A durable financial power of attorney names an agent to handle money, property, taxes, benefits applications, and similar decisions on the principal's behalf. 'Durable' means it remains effective if the principal becomes incapacitated. Most states recognize either an immediate POA (the agent can act starting now) or a springing POA (the agent can act only after a triggering event, usually a physician's written finding of incapacity).
This is the document a bank will ask for the morning a parent's checking account needs attention. Without it, the family ends up filing for guardianship — a process that takes months, costs thousands, and is public. With it, the family can act in an afternoon.
Document two: healthcare power of attorney (also called a healthcare proxy)
A healthcare power of attorney names an agent to make medical decisions if the principal cannot. Some states call this a healthcare proxy or a medical durable power of attorney; the names vary, the function is the same. The healthcare agent has the authority to consent to or refuse treatment, choose providers, access medical records (in coordination with HIPAA authorizations), and make end-of-life decisions consistent with the principal's known wishes.
Many states allow the same person to be named on both the financial and healthcare POAs, or different people. There are good reasons to do either. The conversation about who to name is often more important than the document itself.
Document three: advance directive or living will
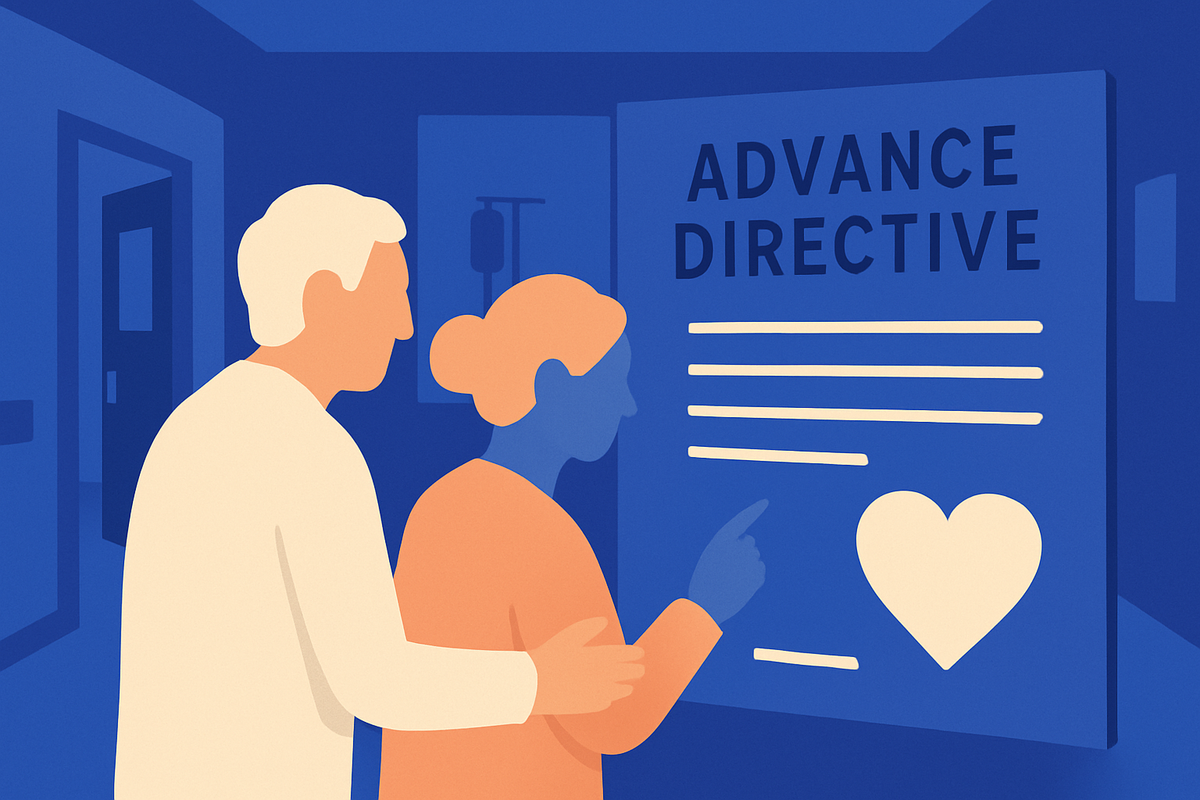
The advance directive (sometimes called a living will) is a written statement of the principal's wishes about life-sustaining treatment in specific medical situations — for example, terminal illness, permanent unconsciousness, or end-stage dementia. The healthcare proxy is who decides; the advance directive is what the principal would want. Most states publish their own statutory advance-directive form; some are short, some are long, some allow attached personal statements.
The advance directive is also the legal vehicle for preferences around feeding tubes, mechanical ventilation, dialysis, antibiotics in late-stage dementia, and the threshold at which the principal would want care shifted from cure to comfort. It does not replace conversation; it is the artifact a difficult conversation produces.
A note on POLST and MOLST: Some states use Physician Orders for Life-Sustaining Treatment (POLST or MOLST) for patients with serious illness. POLST is a medical order signed by both the patient (or surrogate) and the clinician, effective immediately, and meant to travel with the patient across settings. It complements — does not replace — the advance directive.
Document four: HIPAA authorization
Federal HIPAA law restricts who can access a patient's medical information. A signed HIPAA authorization names the family members (or others) the parent permits to talk to doctors, see records, and receive billing information. Without it, even an adult child holding a POA may run into clinicians who decline to share information beyond emergencies.
Most healthcare systems have their own HIPAA forms; an elder-law attorney can also draft a portable HIPAA release that travels with the family. The form is short, the conversation is short, and the absence of the form is the surprisingly common reason an adult child cannot get information they need.
Document five: will (and possibly a revocable trust)
The will is the document people start with — and finish with. It directs what happens to the parent's assets after death, names an executor, and (if relevant) names guardians for minor children or dependent adults. For larger or more complex estates, a revocable living trust can avoid probate, provide privacy, and ease administration; for many simpler estates, a well-drafted will is sufficient. An elder-law or estate-planning attorney can advise on whether a trust adds enough value to justify its cost in your specific state and situation.
The will is important. It is also the last document the family will use, often years after the others have already been used many times. Building the will before the other four is the most common reason families have a binder full of paperwork and no usable way to help their parent the year before they pass.
The order most families build them in
If everything is being built at once, the typical sequence is: financial POA, healthcare POA, advance directive, HIPAA authorization, then will (and trust if applicable). The first four are the documents most often needed during a parent's life. The fifth is the document needed after. Done well, all five are signed in a single attorney's-office visit; done as a family triage in a crisis, each one costs more and is more painful to produce.
The conversation about who to name on the POAs and what to put in the advance directive is often more important than the documents themselves. For the related piece on how to have that end-of-life conversation, see How to talk to your parent about end-of-life wishes. For the related piece on the POA-vs-guardianship distinction, see POA vs. Guardianship: what's the difference and why it matters. For the broader playbook this conversation feeds into, see The Legal and Financial Checklist for Aging Parents. For the longer pillar of related guides, the Legal & Financial hub has the full set.
A note on what helps: Aging Sidekick can help you turn the family conversation about who-decides-what into one printable summary an elder-law attorney can read in five minutes — who is named, what is missing, what is still under discussion. We organize; the attorney drafts the five documents. Free to start.
Start your aging-parent legal & financial checklist
Aging Sidekick walks you through the documents, decisions, and benefits programs that matter for your specific situation — not a generic checklist. It's not legal or financial advice; it's an organized starting point for the conversation with your attorney or advisor.
Start your checklistSee how Aging Sidekick works →